
Table of Contents
- Introduction
- What is Home Loan Prepayment?
- Types of Prepayment
- Partial Prepayment
- Full Prepayment
- Benefits of Home Loan Prepayment
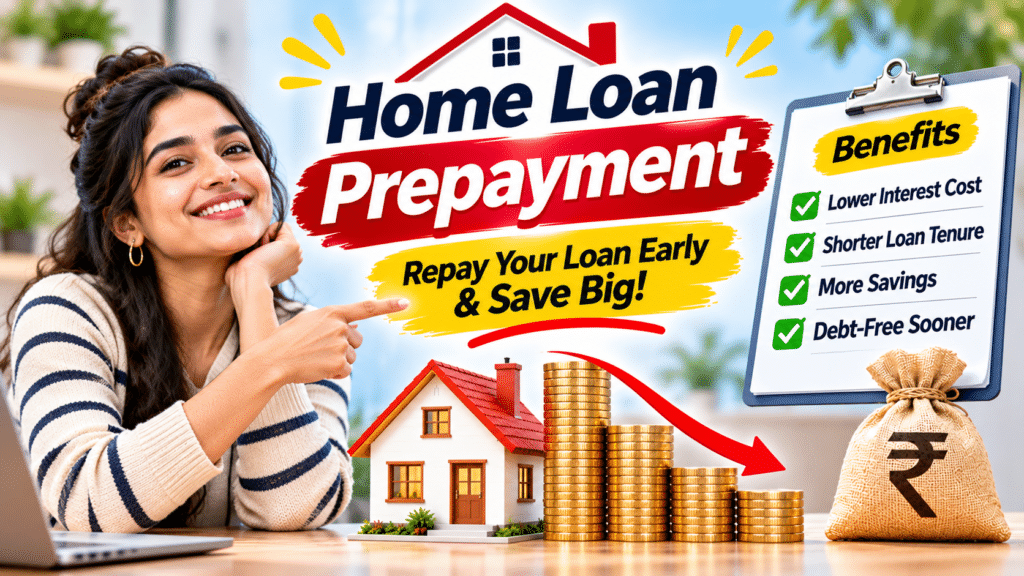
- Saves Interest
- Shortens Loan Tenure
- Improves Financial Freedom
- Factors to Consider Before Prepayment
- Smart Prepayment Strategies
- FAQs
- Does prepayment reduce EMI?
- Is prepayment always beneficial?
- Conclusion
Introduction
A home loan usually continues for many years, and borrowers often look for ways to reduce their interest burden. Prepayment allows borrowers to repay part of their outstanding loan before the scheduled tenure.
What is Home Loan Prepayment?
Home loan prepayment means paying an additional amount towards the outstanding loan principal before the completion of the loan tenure.
It can be:
- Partial prepayment
- Full repayment
Types of Prepayment
Partial Prepayment
The borrower pays an extra amount while continuing regular EMIs.
Benefits:
- Reduces principal
- Lowers interest burden
Full Prepayment
The borrower clears the entire outstanding loan amount before maturity.
Benefits of Home Loan Prepayment
Saves Interest
Reducing principal earlier can reduce total interest payable.
Shortens Loan Tenure
Borrowers may finish repayment earlier.
Improves Financial Freedom
Early repayment reduces long-term debt obligations.
Factors to Consider Before Prepayment
- Emergency fund availability
- Alternative investment opportunities
- Prepayment charges
- Loan interest rate
Smart Prepayment Strategies
- Use annual bonuses
- Make occasional lump-sum payments
- Increase EMI when income rises
FAQs
Does prepayment reduce EMI?
It can reduce EMI or loan tenure depending on lender options.
Is prepayment always beneficial?
It depends on interest savings and financial circumstances.
Conclusion
Home loan prepayment can help reduce debt faster, but borrowers should balance repayment with other financial goals.