
Table of Contents
Introduction
Many buyers choose under-construction properties because they may offer flexible payment options and lower initial costs compared to completed homes.
However, purchasing such properties requires careful evaluation of builder credibility, approvals, and loan terms.
What is an Under-Construction Property Loan?
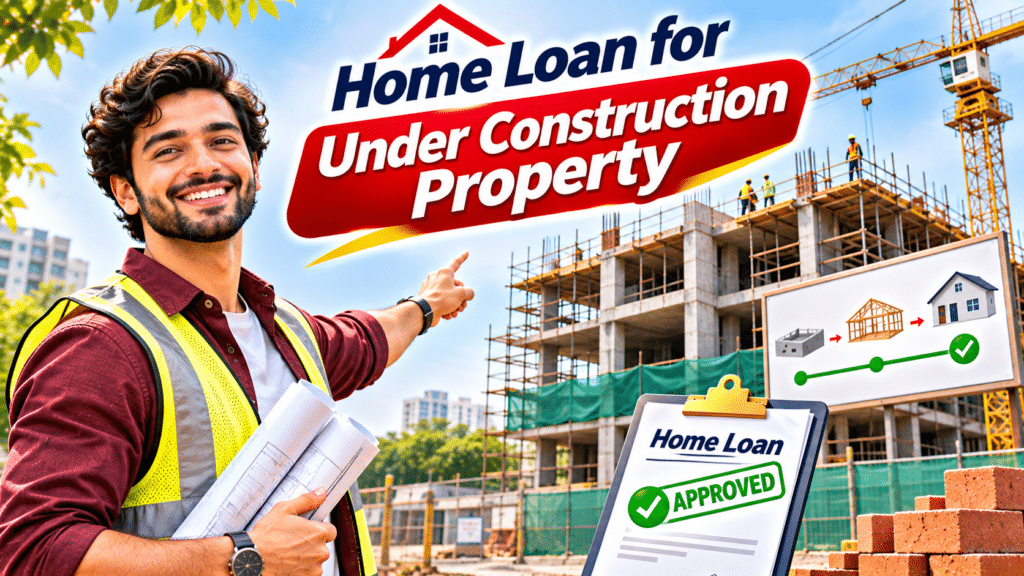
It is a home loan provided for purchasing a property that is still being developed.
The loan amount may be released in stages based on construction progress.
How Does Disbursement Work?
Unlike completed properties, lenders may release funds according to construction milestones.
Example:
- Foundation completion
- Structural completion
- Final stages
Benefits
Lower Initial Payment
Payments are linked with construction progress.
Early Property Investment
Buyers may purchase properties before completion.
Flexible Payment Structure
Stage-wise payments may ease financial planning.
Risks to Consider
Construction Delays
Project delays may affect possession timelines.
Builder Reliability
Check builder history and approvals.
Additional Costs
Consider maintenance and other charges.
Checklist Before Buying
Verify:
- Builder reputation
- Legal approvals
- Project registration
- Completion timeline
- Loan agreement terms
FAQs
Do banks provide loans for under-construction properties?
Yes, if property and borrower eligibility conditions are satisfied.
Is EMI charged immediately?
It depends on disbursement amount and lender terms.
Conclusion
Home loans for under-construction properties can help buyers achieve ownership, but proper research and verification are essential.