
Table of Contents
Introduction
A joint home loan allows two or more individuals to apply together for purchasing a property. It is commonly used by spouses, family members, or co-owners to increase borrowing capacity.
What is a Joint Home Loan?
A joint home loan is a loan where multiple applicants share responsibility for repayment.
All applicants are responsible according to loan agreement terms.
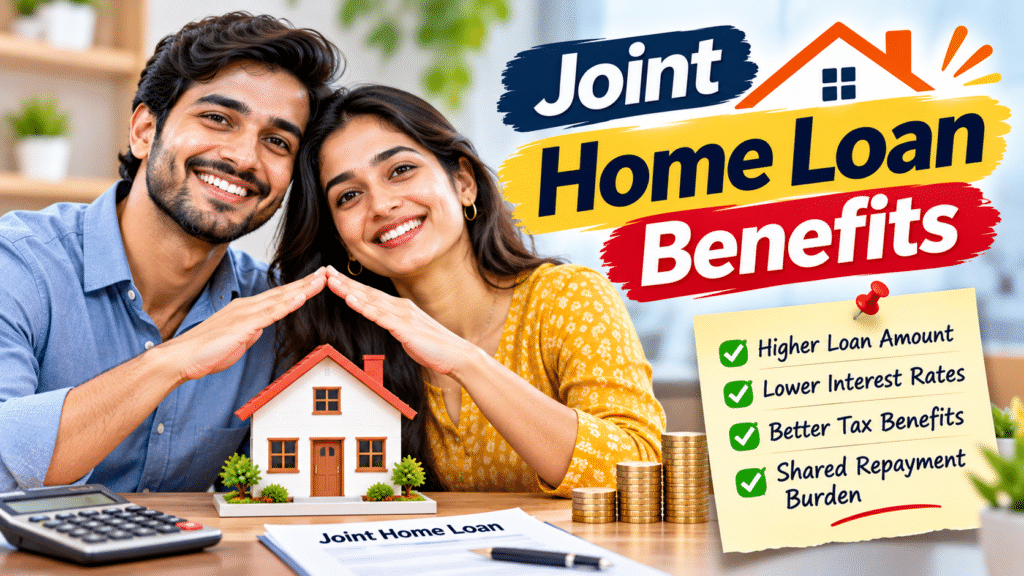
Benefits of Joint Home Loans
Higher Loan Eligibility
Combining incomes may increase borrowing capacity.
Shared Repayment Responsibility
EMI burden can be divided between applicants.
Possible Tax Benefits
Eligible co-borrowers may claim benefits according to applicable tax rules.
Who Can Apply Together?
Common combinations:
- Husband and wife
- Parent and child
- Co-owners
Things to Consider Before applying:
- Understand repayment responsibility
- Maintain clear ownership details
- Discuss financial commitments
FAQs
Is a joint applicant always a co-owner?
Requirements depend on lender policies and property ownership rules.
Does joint loan improve eligibility?
Combining incomes may increase eligibility.
Conclusion
Joint home loans can make property ownership easier by combining financial resources. Applicants should understand responsibilities before signing the loan agreement.